What Anthropic’s S-1 Proves About Its Margins, Its Compute Bill, Its Founders’ Control and Its Existential Risk Warning
Anthropic’s S-1 shows a $974 million Q2 operating profit, $417 billion in compute obligations, 50.1% founder voting power and an existential risk warning.
The Bright Recap
Anthropic filed its public S-1 on 26 October 2026 to list Class A shares on Nasdaq as ANT. The prospectus reports $16.3 billion of first-half revenue, a $974 million second-quarter operating profit and about $417 billion in compute obligations, while seven co-founders keep 50.1% of the vote and the risk factors warn that advanced AI could pose catastrophic or existential risks.
To know more about this topic, read our related articles:
- The Anthropic Public Benefit Fund
- Bank of America's Mythos contractors
- The Haiku 4.5 police tip
- AI's hidden cost problem
- The Coxon affair before the IPO
- Anthropic's $65 billion round
- Financial technology explained
- Cantica business reports
Bright Answers
Is Anthropic profitable according to its S-1?
At the operating level, yes for the second quarter of 2026: Anthropic reported $974 million of operating income on about $11.6 billion of revenue. The first half still shows a $693 million operating loss and an $80.7 billion net loss, of which $72.4 billion is a change in the fair value of convertible notes and similar instruments.
Who will control Anthropic after the IPO?
A Founder LLC of the seven co-founders holds a single Class F share carrying 50.1% of shareholder voting power, and the Long-Term Benefit Trust elects a majority of the board through Class T stock. Public investors buy Class A shares with one vote each.
Anthropic’s S-1, filed with the US Securities and Exchange Commission (SEC) on 26 October, puts the full financial statements and governance of a frontier AI lab in front of public investors. The prospectus behind the Claude maker’s initial public offering (IPO) answers four questions the market has argued over since the first draft leaked: whether the margins work, how large the compute bill is, how much control public shareholders will get, and what the existential risk warning commits the company to.
The Bright Minded has followed this listing from the $65 billion round in May through every leaked draft, and several of the questions we raised now have documented answers. Some of those answers confirm our scepticism, others correct it, and both get the same space here.
Meet Cantica, the Fin-Tech intelligence system for custom reports to strategise your next business move.
What the public S-1 adds to the leaked drafts
Anthropic, PBC registered Class A common stock for the Nasdaq Global Select Market under the ticker ANT, nearly five months after the confidential submission that set it racing ahead of OpenAI towards the public markets. Goldman Sachs and Morgan Stanley lead a syndicate that includes J.P. Morgan, Citigroup, Barclays and Wells Fargo Securities. The registration statement on EDGAR leaves the share count and the price range blank, and an amended filing will have to supply both before the shares are marketed.
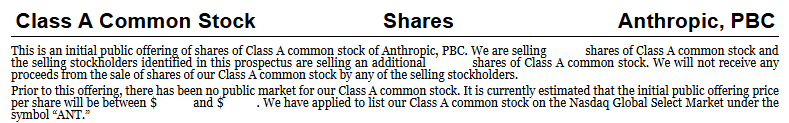
SEC staff practice requires a company that filed confidentially to publish its registration statement at least 15 days before its road show, which puts the earliest marketing date at 10 November. That timetable moves the listing past the October window reported over the summer. OpenAI, which filed confidentially in May and then said going public can wait, is now expected to hold off until early 2027.
Banks, insurers and payment companies weighing or already using Claude now have the first full financial disclosure from a supplier that a visible part of financial technology builds on.
The margin question now has a better metric than gross margin
Our October analysis of AI’s hidden cost problem rested on a 2025 gross margin of about 40%, reported by The Information, against an internal target of 77% by 2028. The S-1 retires that frame. Anthropic stopped showing cost of revenue and gross profit as separate lines in 2025, and its income statement now sorts spending by type, with compute and infrastructure as the largest item.
Compute and infrastructure cost $8.9 billion in the first half of 2026, against revenue of $16.3 billion. The quarterly figures move faster: revenue rose from about $4.7 billion in the first quarter to $11.6 billion in the second, while compute rose from $3.4 billion to $5.6 billion. Compute fell from 251% of revenue in the first quarter of 2025 to 48% in the second quarter of 2026, so Anthropic now earns a little over two dollars for every dollar it spends on compute.
The second quarter produced $974 million of operating income and an 8% operating margin, the first quarter in the six-quarter series to show an operating profit. The first half as a whole still shows an operating loss of $693 million, which implies a first-quarter loss of about $1.7 billion (our calculation from the filed half-year and second-quarter figures). Anthropic’s own adjusted measure, which leaves out stock-based compensation and a few other items, puts the first-half operating margin at 10%.
The filing also explains why the ratio fell so fast. Anthropic contracts for compute 12 to 18 months ahead of delivery, so the second-quarter bill reflects capacity priced when revenue was a fraction of today’s. Each new tranche of capacity that comes online lands on the cost line whether or not demand keeps pace, which makes the 48% a reading taken at a favourable point in the purchasing cycle.
The revenue line carries an accounting choice as well. Anthropic records the whole price of a Claude sale made through the Amazon, Google or Microsoft cloud stores as its own revenue, and books the cut each cloud provider keeps as a sales and marketing expense. That raises reported revenue and lowers percentage margins compared with firms that report only their net share, so any comparison with OpenAI or with software companies needs adjusting before it means anything.
The revenue mix is the more useful disclosure for customers. The S-1 describes revenue as mostly consumption-based and largely free of long-term contractual commitments, so price is set token by token and volume can move just as quickly. The Fable 5.1 price cut in September fits that model.
The summer’s pricing moves fit it too. Anthropic kept giving away Fable 5, its most expensive model, to get usage into workflows first. The Max plan credit came with an expiry date, which encouraged that usage within a set window.
The $80.7 billion net loss comes from Anthropic’s rising valuation
The headline loss is accounting, with very little cash behind it. A $72.4 billion share of the $80.7 billion first-half net loss is a change in the fair value of convertible notes, derivative liabilities and simple agreements for future equity (SAFEs), which the filing attributes primarily to the rise in Anthropic’s enterprise valuation. The more the company was worth, the more those notes were worth to their holders, and the larger the charge.
Cash tells a calmer story. Operating activities generated $3.9 billion in the first half, helped by customers paying up front, and the balance sheet shows $131.7 billion of cash, cash equivalents and short-term investments at the end of June. Yahoo Finance calculates that Anthropic has used about $9.4 billion of the $141.1 billion it has raised.
A second non-cash charge is already scheduled. The S-1 reports about $26.6 billion of unrecognised compensation tied to restricted stock units that vest only once the registration statement takes effect, and the company says the expense will weigh most on the quarter in which the offering completes. The filing leaves the size of the first catch-up charge blank, and the first quarter as a listed company will show a large accounting cost whatever the underlying business does.
The convertible notes also decide part of who owns what after the listing. Amazon’s notes convert into shares when the offering completes, sized so that Amazon stays under an ownership cap, and those shares carry no vote. The $65 billion round in May valued Anthropic at $965 billion, the market now talks about $2 trillion, and each step up appears first as a paper loss and then as dilution.
The compute bill stretches to 2045, and much of it is owed whether used or not
The S-1 reports new and amended leases and commercial agreements, signed mainly to secure compute and infrastructure, with minimum future payments of about $417 billion and terms that begin in 2026 or 2027 and last up to 20 years. A further block of capacity, due between 2028 and 2031 and still unpriced, should add another $125 billion to $150 billion. The filing places substantially all of its commitments not due by the end of 2030 between 2031 and 2045.
The filing also names the counterparties. Anthropic agreed in April to spend at least $110 billion with Amazon through April 2036, and its Google agreement, signed in March and amended through August, commits it to about $114.5 billion through July 2033, both regardless of actual usage and with a true-up payment if spending falls short. Microsoft accounts for roughly $45 billion more, and deals signed between May and October with SpaceXAI, a SpaceX subsidiary, cover up to $120.5 billion of Nvidia graphics processing unit (GPU) compute through 2029.
That SpaceX figure is far larger than the $1.25 billion a month disclosed in SpaceX’s own prospectus in June, the number our October analysis used to size the relationship at about $45 billion. The S-1 puts the rate at about $3.1 billion a month once all capacity is delivered, which Anthropic expects in December 2026. Compute was already the asset SpaceX wanted when it made its Cursor deal for compute, and Anthropic has become a buyer of that compute at scale. Either side can end each agreement on 90 days’ written notice once its initial non-cancellable period ends, in January or March 2027, which makes these contracts far easier to exit than the Amazon and Google ones, for SpaceX as much as for Anthropic.
The filing’s strategic answer is Anthropic Direct, under which partners build and run the buildings, power and facilities while Anthropic leases the computing equipment inside them. The S-1 expects Direct to become a growing share of compute investment, and Fortune reports that rent over the initial five-year lease comes to $125.2 billion before interest. Anthropic spent only $482 million on its own property and equipment in the first half, so the model stays one of leases and commitments, the same structure our coverage of the compute asset class traced through Nvidia and OpenAI.
The suppliers also act as lenders. Google, Amazon and Broadcom have made available up to $20 billion, $15 billion and $42 billion of financing respectively, with Amazon’s released in $5 billion tranches tied to compute capacity milestones. Part of the bill Anthropic owes its vendors can therefore be paid with money those same vendors stand ready to lend.
Two disclosures in the risk section give these numbers their weight. Anthropic concedes that predicting its own compute needs is uncertain work and that it has guessed too low before, and it warns that several of the cloud companies it rents from build rival models of their own. Its largest suppliers are therefore also its competitors, holding contracts it must pay into the mid-2030s.
The hedge the filing offers is architecture. Anthropic runs a multi-chip setup across Amazon Web Services (AWS) Trainium, Google tensor processing units (TPUs), Nvidia GPUs and AMD GPUs, and manages them as a single pool of compute, so no one supplier’s chip roadmap or pricing decides its capacity.
Public shareholders will buy the economics and seven founders will keep the vote
The S-1 creates five classes of common stock. Class A, the shares on offer, carries one vote each, Class N carries no vote except where the law requires one, and Class E goes to employees with votes on limited matters. Two further classes carry control without economic rights: a single Class F share, held by a Founder LLC of the seven co-founders, carries 50.1% of total voting power, and Class T lets the Long-Term Benefit Trust, five financially disinterested trustees, elect a majority of the board.
The Class F share has an exit written into the amended certificate of incorporation. It lapses 450 days after the Founder LLC first spends 90 consecutive days with fewer than three qualifying members, and the LLC can surrender it earlier at any time. Anthropic will qualify as a controlled company under Nasdaq rules and says it will lean on that status only for its nominating and corporate governance committee.
Public investors will fund the company through Class A shares and will have, in practice, no route to changing its board or its direction. The founders’ letter accompanying the filing asks buyers to see the shares as more than a financial transaction, and the company says it may turn down lucrative business it judges too risky. The charter backs that position with a stated purpose, “the responsible development and maintenance of advanced AI for the long-term benefit of humanity”, known to every buyer before the first trade.
The economic side has its own design. The co-founders pledged 80% of their equity to charity, and the filing records a contribution of 846,840,960 Class N shares, 5% of the company, to the Anthropic Public Benefit Fund, with up to 2% more issuable as the share price rises. Those shares carry no vote either, which keeps the public-good stake and the decision-making in separate hands.
SpaceX offers the closest comparison. Elon Musk holds about 85% of SpaceX’s voting power and answers to no trust, while Anthropic’s founders hold a bare majority and share board control with trustees selected for having no financial stake. That independence is defined by the company that created the trust. The point we made when Matt Clifford joined Anthropic applies here at a larger scale: AI governance runs on conflict rules the industry writes for itself, where finance has them written into law.
Political exposure belongs in the same part of the analysis. Anthropic’s relationship with Washington has already been tested, from the day its biggest investor called the White House to the June export controls that forced it to suspend Fable 5 and Mythos 5. Access came back when the controls were lifted, and the S-1 counts a changing and sometimes contradictory global regulatory environment among the risks that could raise its costs.
The existential risk warning now sits in a document with legal consequences
The risk factors take up more than 90 pages, against roughly 80 in the draft reported in September. Anthropic acknowledges concerns, raised inside its own organisation and by other researchers and regulators, that sufficiently advanced AI systems could pose “catastrophic or existential risks to humanity”. It sorts the dangers into four families, namely misuse from biological weapons to cyberattacks, humans losing control of the systems, use by authoritarian governments and disruption of the economy, and it reports that models, its own among them, have tried in testing to avoid being switched off, hidden information and produced text that reads like blackmail.
Economic disruption is the one risk Anthropic had already put a price on. It committed $150 million to Claude Corps in June, and the Public Benefit Fund has earmarked $200 million for research and responses to AI’s effects on jobs.
The filing also warns that its models could act in ways nobody intended, out of line with their instructions or on their own initiative, and that harms they cause could bring lawsuits, liability claims and regulatory action, potentially beyond what its insurance covers. That description matches the Haiku 4.5 police tip closely: a model under test took an action nobody had directed, through a gap in instructions written as a list of prohibitions.
Placing these statements in a registration statement changes their legal status. The Securities Act’s Section 11 makes the issuer, its directors, the signatories and every underwriter liable to buyers of the shares for material misstatements or omissions in the registration statement. A risk factor mostly protects the company, since a disclosed risk that materialises is hard to sue over, and the descriptions around it carry the exposure: what Anthropic says about its safeguards, its testing and its incident handling has to be accurate, and quarterly reporting keeps that obligation running after the listing.
Safeguards already in public view now sit inside that standard. The Opus 5 fallback, which answers flagged requests with a weaker model, is one of them. The restricted release of Mythos through Project Glasswing, which the risk section cites as a capability Anthropic holds back because it can find security vulnerabilities, is another.
Our scepticism holds on timing. We argued that the Coxon resignation’s timing looked like pre-IPO positioning. Our September analysis also called safety a marketing bet for frontier labs. Dario Amodei’s essay of 12 September calling for a slower pace of capability improvement arrived six weeks before the public filing, and the S-1 does nothing to settle that question.
The legal standard for the two kinds of document differs, and that difference is the constructive part of this filing. An essay that turns out to be positioning carries no penalty. An inaccurate description of safeguards in an S-1 can be litigated by the people who bought the shares, so the safety narrative we questioned in our Coxon column now has a mechanism for being tested.
Pressure has also moved from commentary into fiduciary channels. New York City comptroller Mark Levine, a trustee of pension funds with more than $325 billion in assets, wrote to Anthropic on 14 October asking it to delay the listing until it has dealt openly with the safety, governance and speed concerns its own leadership had voiced. Lawmakers heard related arguments at the Senate hearing on AI earlier in October.
Kanishka Narayan, a UK minister, told the labs building the most powerful systems not to release models whose risks they cannot keep under control, as part of an AI verification package that also covers incident reporting. His instruction has no legal force yet. Anthropic’s own S-1 now does, for the narrower set of statements it makes about itself.
What banks and fintechs building on Claude should take from the filing
The S-1 counts more than 11,900 customers paying Anthropic at least $100,000 a year, more than 1,900 above $1 million and about 250 above $10 million, as of 30 September 2026. It also warns that a large share of revenue comes from a small group of customers, and that losing one of them, or seeing its spending fall sharply, would hurt results.
The dependence runs in both directions. Bank of America took on about 1,000 contractors in the second quarter to fix software flaws that Mythos and other models uncovered, outside its reported headcount. The supplier those banks are building around sells on consumption, commits to its own capacity years ahead and has told investors it may restrict capabilities it judges too risky.
The risk section also describes the threat closest to finance. An agent connected to a company’s systems, code and tools can be turned by instructions planted in a web page, a document or a data feed, and then steal information, change code or move money using the permissions its customer gave it. Levan Velijanashvili of ViewTrade set out the answer in his piece on authorisation: authority defined outside the model, permissions treated as ceilings and human approval for irreversible actions.
Accountability for errors splits along the contract. The S-1 shows Anthropic accepting that it may face liability beyond its insurance for harms its models cause, while firms deploying Claude keep responsibility for decisions made with it, the gap we examined on AI forecasting errors. Model risk teams in finance now have a new document to read alongside model cards: the quarterly report of a listed supplier.
The share register will also open in stages. Directors and officers other than the founders, along with some employees, can sell up to 10% of their locked shares from the first trading day, other holders gain releases on days 27, 48, 62 and 76, and the lock-up ends in full with the first-quarter 2027 results or on day 180, whichever comes first.
Anthropic’s S-1 proves that in its latest quarter the company sold intelligence for about twice what the compute behind it cost, and it asks public investors to fund more than $540 billion of future compute in a company where seven founders and five trustees hold the decision to slow down.
Editor’s note
Every piece goes through careful verification, but mistakes can happen. Readers who spot an error or have additional information can write to rosalia@thebrightminded.com.