Machine-to-Machine Payments: Why a $0.30 Card Fee Stops AI Agents Paying for Content
Coinbase Institute’s machine-to-machine payments paper shows why card fees fail AI agents paying per request, and how x402 and stablecoins price one request.
The Bright Recap
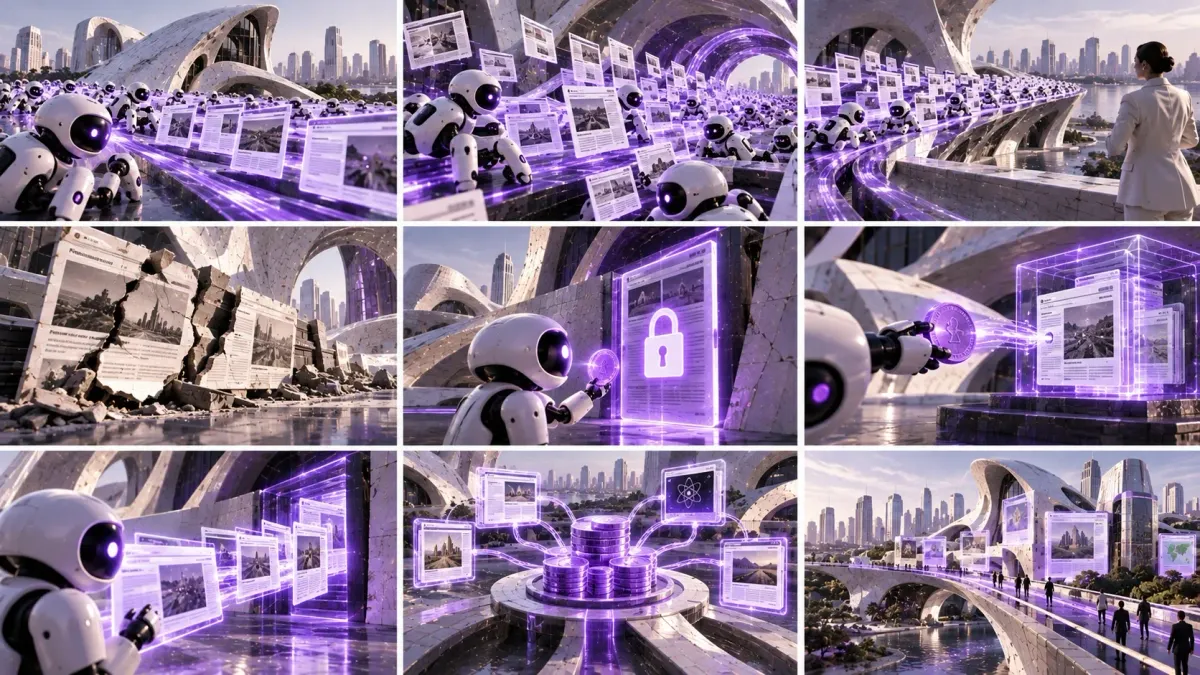
A fixed card fee of $0.30 is 300 times the price of a $0.001 request, so AI agents cannot use cards to pay websites per page. A Coinbase Institute paper on machine-to-machine payments, released on 7 October 2026, sets out how the x402 standard and stablecoins let software pay for one piece of data in about two seconds, for a fraction of a cent.
To know more about this topic, read our related articles:
- When AI agents become paying customers
- Mastercard gives agents a spending identity
- The authorisation gap in autonomous payments
- Blockchain explained
- Financial technology explained
- Cantica business reports
Bright Answers
What are machine-to-machine payments?
They are payments that software makes to other software without a person approving each one, often for a fraction of a cent, such as an AI agent buying a single data point from a data provider.
Why can't AI agents use cards for tiny payments?
Because a fixed card fee of around $0.30 costs more than the request itself when the request is priced at a tenth of a cent. The Coinbase Institute calculates that the cheapest card option keeps fees at or below 5% only from about $1.19 upward.
Software now makes most of the requests for web pages, and it sees no adverts and buys no subscriptions, the two ways much of the web pays for itself. Bots made 60.4% of requests for web pages in August, against 39.6% from humans, according to Cloudflare data cited in a machine-to-machine payments paper the Coinbase Institute published on 7 October.
The obvious answer is to charge the software a tiny amount each time it reads a page or fetches a data point. The paper explains why today’s payment systems cannot do that: a card payment processed by Stripe in the US carries a fixed fee of $0.30, which is 300 times the price of a $0.001 request. Its proposal is a standard called x402, which lets software pay per request in stablecoins, digital tokens that hold a steady value against the dollar, for a fraction of a cent.
Meet Cantica, the Fin-Tech intelligence system for custom reports to strategise your next business move.
Software reads the web but sends few readers back
Search engines and websites had a working arrangement: the engine read a page, sent people to it, and those people saw the adverts that funded it. Artificial intelligence (AI) systems read pages to answer a question on the spot, and Cloudflare evidence cited in the paper shows them reading thousands of pages for each visitor they pass on. Press Gazette figures used in the paper show Google search sending roughly a third less traffic to publishers worldwide between November 2024 and November 2025.
Big publishers can sign licensing deals with AI companies. A local news site or a specialist research archive has neither the leverage for a deal nor a way to send a crawler an invoice. The same applies to anything a firm puts online to be found, such as a law firm’s regulatory updates or a consultancy’s sector research.
The companies that run the web’s plumbing have started to act. Cloudflare, which handles traffic for about a quarter of all websites, set 15 September as the date from which it blocks AI training and agent crawlers by default on ad-funded pages for new sites and free-tier customers, according to the paper, while still letting search crawlers in. It has offered publishers a pay-per-crawl option since July 2025. Amazon Web Services (AWS) is moving the same way, with tools that treat agents as paying customers.
A $0.30 card fee is 300 times a $0.001 purchase
A fixed fee is charged on every card payment regardless of its size. Stripe’s is $0.30 in the US, so on a $60 food shop it adds half a percentage point, which nobody notices. The same fee on a $0.001 request to an application programming interface (API), the connection one program uses to ask another for data, is 300 times the price, or 30,000%.
The Coinbase Institute paper calculates the smallest payment each method can handle while keeping fees at or below 5% of the amount.
| Payment method | Smallest payment with fees at or below 5% |
|---|---|
| Online credit card | about $5 to $14.29 |
| Card on small-ticket pricing | about $1.19 |
| Regulated US debit card | about $4.44 |
| Bank transfer | $5 to $10 |
| Instant payment (FedNow) | about $0.90 |
| Stablecoin on a low-cost network | about $0.002 to $0.02 |
Source: Coinbase Institute, Machine-to-machine payments in the AiFi era. Figures show the smallest payment at which each method’s fees fall to 5% of the amount.
The cheapest card option needs a payment of about $1.19 before its fees drop to 5%, while a stablecoin payment gets there at two-tenths of a cent. Disputes widen the gap. The paper puts the cost of handling one card dispute at $15 or more, and close to $128 once every cost is counted, which by our calculation is 128,000 times a $0.001 sale.
Many of the sellers software would buy from also struggle to accept cards at all. A developer running a data service alone, or a small archive, usually has to show a registered company, a record of past payments and a website, and often has to guarantee the account personally, before a card processor will take them on.
How x402 lets software pay per request
The rules browsers and servers use to exchange pages, the Hypertext Transfer Protocol (HTTP), have included an error code called 402 Payment Required since the 1997 version. The code was set aside for later use, and the current version, published in 2022, still leaves it that way.
x402, an open standard Coinbase introduced in May 2025, puts that code to work. A piece of software asks for a page or a data point and gets back a 402 reply showing the price and the payment options. It compares the price with the budget its owner allowed, signs a payment and asks again, and the server checks the payment and hands over the content.
The paper’s example is a delivery-routing program that needs rainfall data for a stretch of road that big weather services cover poorly, and buys one reading from a small sensor network for a fraction of a cent. Payment and delivery take about two seconds in total, the network charges hundredths of a cent, and nobody opens an account or sends an invoice. The money in the paper’s examples moves over public blockchain networks, though the standard does not tie users to one token, network or provider.
Stablecoins handle tiny payments and cards keep the large ones
The paper picks stablecoins as the best payment method available today for these tiny transactions. A transfer on a low-cost network costs between $0.0001 and $0.001, confirms within seconds at any hour and across borders, and can be limited by spending rules built into the digital wallet itself.
The authors single out one more feature: a wallet that can pay can also be paid. Software that buys data can therefore sell its own work too.
Cards stay in the picture for larger, less frequent purchases, and the card networks are adapting to software customers as well. Mastercard, for example, has given agents a spending identity, with limits it enforces and settlement in both cards and stablecoins.
Who answers for software that spends money
Banks and card companies identify customers by name, tax number and address, and none of their systems has a built-in way to record that a program is spending on someone’s behalf within agreed limits. The paper suggests that a seller should only need confirmation that a responsible person or company stands behind the program and has set its limits.
Checks would then grow with the money at stake, and a program verified once could show the same proof to every seller. The paper’s example contrasts a program spending fractions of a cent on a $5 monthly budget with one moving tens of thousands of dollars, and argues the first deserves far lighter checks. The open question becomes what the program was allowed to do, which security chiefs already describe as the weak point for agents with financial authority.
Coinbase wrote x402 and now shares it with the card networks
Coinbase has a stake in this argument. It created x402, its developer tools handle the payment in the paper’s example, and the sample transaction published with the paper runs on Base, a network Coinbase built. The paper itself notes that stablecoin activity is concentrated in a few dollar tokens, and asks regulators to keep room for several issuers, tokens and networks.
Control of the standard has already spread. The x402 Foundation, run under the Linux Foundation, began formal operations in July with 40 members, among them Visa, Mastercard, American Express, Stripe, Adyen, Google, AWS and Cloudflare. Stripe and the three card networks, whose pricing sits behind the card rows of the table above, now help maintain the alternative to them.
The paper also asks regulators to let software payments run directly on money from licensed issuers, without requiring them to pass through licensed marketplaces. That choice determines whether fintech companies building payment tools for software can connect to a shared standard or must apply for space inside a platform someone else controls.
A $0.30 card fee was designed for a person paying at a till, and for software it puts anything worth less than about a dollar out of reach.
Editor’s note
Every piece published on The Bright Minded goes through careful verification, but mistakes can happen. If you spot an error, have additional information, or want to flag anything, write to rosalia@thebrightminded.com.