SoFi Earn Tokenized Deposit Pays 4.40% and Converts 1:1 Into the Bank’s Own Stablecoin
SoFi Earn is a tokenized bank deposit paying 4.40% APY that converts 1:1 into SoFiUSD, a stablecoin whose issuer the GENIUS Act bars from paying yield.
The Bright Recap
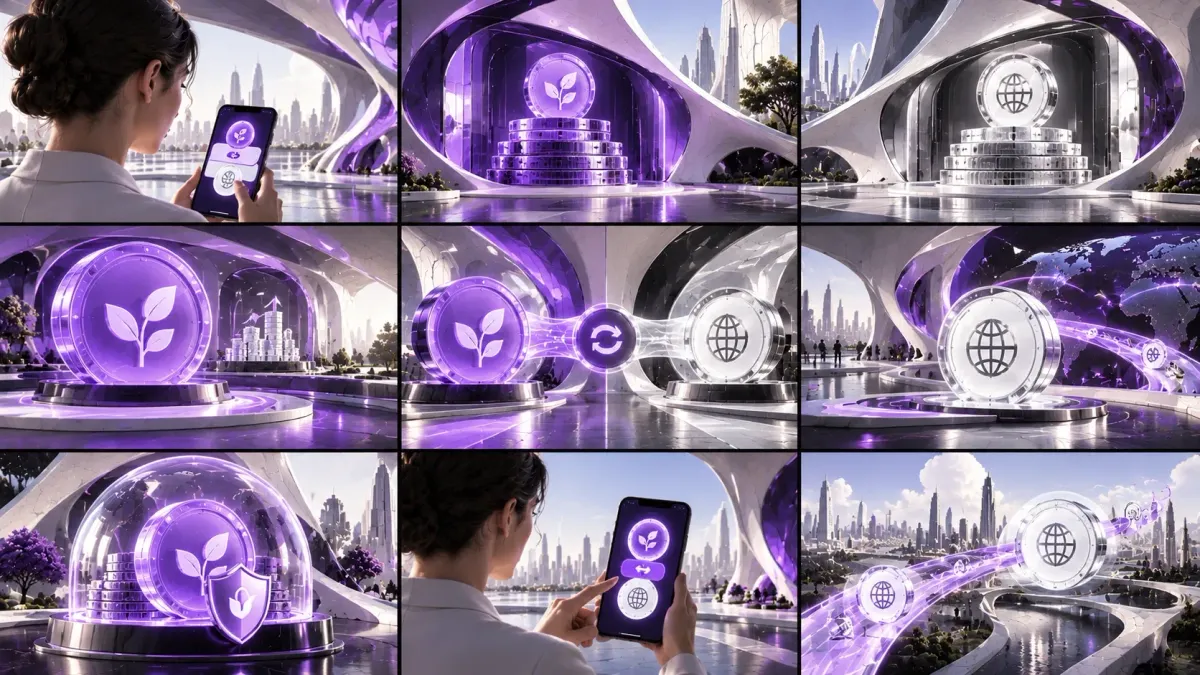
SoFi Earn (SOFIE) is a tokenized deposit at SoFi Bank, N.A. that pays a variable 4.40% APY, is FDIC-insured up to the applicable limits and converts 1:1 into SoFiUSD, the bank's stablecoin.
SoFi launched it on 22 October 2026, one day after the OCC finalised its GENIUS Act rule, which keeps the ban on stablecoin issuers paying holders yield. Deposits fall outside the definition of a payment stablecoin, so the deposit form can earn interest and carry deposit insurance while the stablecoin form moves at any hour.
To know more about this topic, read our related articles:
- What the GENIUS Act yield ban covers
- HSBC's tokenised deposits in the UAE
- The bank lobby's stablecoin yield fight
- Blockchain explained
- Financial technology explained
- Cantica business reports
Bright Answers
What is the difference between a tokenized deposit and a stablecoin?
A tokenized deposit such as SOFIE is a bank deposit recorded as a digital token, so it can pay interest and is covered by FDIC insurance up to the applicable limits. A payment stablecoin such as SoFiUSD is not a deposit and has no deposit insurance, and from 18 January 2027 the GENIUS Act bars its issuer from paying holders interest for simply keeping it.
Who can use SoFi Earn?
SoFi is rolling SOFIE out to SoFi Crypto members through November 2026. The 4.40% APY is variable, dates from 20 October 2026, needs no minimum balance and can be reduced by fees.
A dollar held by a crypto user can now sit in two digital forms at the same bank, and the form it takes decides whether it earns interest. The SoFi Earn tokenized deposit (SOFIE), launched on 22 October 2026, pays a variable 4.40% annual percentage yield (APY), carries Federal Deposit Insurance Corporation (FDIC) insurance up to the applicable limits, and converts one to one into SoFiUSD, the stablecoin issued by the same bank. The interest sits with SOFIE, and a member who wants to buy crypto or send money to an outside wallet converts into SoFiUSD first, so the product puts the choice between interest and mobility on a single conversion.
The launch came the day after the Office of the Comptroller of the Currency (OCC) finalised its rule implementing the GENIUS Act, the US stablecoin law that bars issuers from paying interest to holders. SoFi’s announcement does not mention the law. Its product pair shows how a bank can work within it.
Meet Cantica, the Fin-Tech intelligence system for custom reports to strategise your next business move.
Why the deposit can pay and the stablecoin cannot
The GENIUS Act bars a stablecoin issuer from paying a holder interest or yield solely for holding, using or retaining its payment stablecoin. The OCC’s final rule, covered in our analysis of the GENIUS Act final rule, keeps that ban and takes effect on 18 January 2027. The Act’s definition of a payment stablecoin, which the rule applies, leaves out bank deposits, including deposits recorded on a distributed ledger.
A bank deposit can pay interest like any savings account, and turning it into a token leaves its legal nature unchanged. SOFIE can earn 4.40% because the law treats it as a deposit, while SoFiUSD is a stablecoin, and from January its issuer cannot pay holders for simply keeping it. The $5,000 in SoFi’s own example would earn about $220 over a full year at the current rate before any fees, a figure that is our own calculation and assumes the variable rate does not change.
What SoFi launched
SoFi describes SOFIE as the first and only tokenized deposit that a US national bank offers to consumers. Each SOFIE stands for one dollar on deposit at SoFi Bank, N.A., and the SoFi announcement says in its disclosures that the token is a liability of the bank and not a payment stablecoin. The 4.40% rate dates from 20 October and can move at any time, with no minimum balance required and fees able to reduce what a member earns.
Members of SoFi Crypto will receive access through November, and SoFi counts SOFIE as its fifth crypto offering in under a year. SoFiUSD came first, in December 2025, and SoFi presents it as the first stablecoin to come from a US national bank. The company’s example has a member saving for a future crypto purchase hold the money in SOFIE and move it into SoFiUSD at the moment of buying or sending it out.
What stands behind each form of the dollar
The protection changes at the same moment as the interest. SOFIE is covered as a deposit under the FDIC’s standard rules, generally up to $250,000. SoFiUSD travels on blockchain rails at any hour, but it is not a deposit and has no deposit insurance, so its holder depends on the issuer’s duty to redeem at par from the reserves behind the token.
The OCC’s rule requires an insured national bank that wants to issue a payment stablecoin to do so through a subsidiary approved by the agency, and that issuer must hold reserves at least equal to the stablecoins outstanding and generally meet redemption requests within two business days. A SoFi member converting inside the app deals with SoFi on both sides of the conversion. A buyer who picks up a stablecoin on an exchange becomes the issuer’s customer only on asking to redeem it.
Tokenized deposits outside the crypto app
HSBC’s tokenised deposits operate in Hong Kong, Singapore, Luxembourg, the UK, the US and, since June 2026, the United Arab Emirates, where Ant International said on 6 October that it had used the service for dirham transfers and for dollar transfers to Hong Kong and Singapore. SOFIE brings the same kind of instrument to an individual saving inside a crypto account, and SoFi reports 15.8 million members.
The idle money SoFi is aiming at
Anthony Noto, SoFi’s chief executive, argued that a large share of the money held in digital assets earns nothing. SoFi backs the point with Federal Reserve research putting 21.2% of stablecoins, worth about $64 billion, in idle wallets. The figure matches a Kansas City Fed briefing by Franklin Noll, published on 10 April 2026, which classed 21.2% of stablecoins as idle, meaning tokens left in wallets that are seldom used, lost or forgotten, or kept as small savings.
The briefing measured a market of $300.5 billion on 14 November 2025, and 21.2% of that comes to about $64 billion. Noll writes that data on idle stablecoins are scarce and that the share is his own assumption, lowered from a 2024 Forbes estimate of 30%. He says the strongest data cover stablecoins used as trading assets, 48.8% of the total, and puts payments at 0.7%.
The deposit question banks raised
The American Bankers Association, in its lobbying on Section 404 of the CLARITY Act, the market structure bill that later failed in the Senate, warned that rewards resembling interest on stablecoins could draw money away from bank deposits. SoFi’s design keeps money that is waiting to be spent on crypto on the bank’s balance sheet as a deposit, and it becomes a stablecoin only when the member converts it.
The arrangement has limits that a member should weigh. The rate is variable, fees can reduce it and only SoFi Crypto members can use it, while a dollar converted into SoFiUSD stops earning the deposit rate and leaves deposit insurance behind.
What SoFi’s design shows fintech users
Tokenized money is often discussed in fintech as a question of technology. SoFi’s product pair turns it into a set of terms a user can compare: interest, insurance and opening hours. A professional asked about digital dollars can now point to a single bank that offers both forms and show what each one pays.
SoFi has made the GENIUS Act’s yield ban visible as a conversion button: on the deposit side a dollar earns 4.40% under FDIC insurance, on the stablecoin side it can leave the bank at any hour as a token whose issuer the law bars from paying holders for holding it, and the money stays a deposit at SoFi until the member presses the button.
Editor’s note
Every piece goes through careful verification, but mistakes can happen. Readers who spot an error or have additional information can write to rosalia@thebrightminded.com.