ESMA Stablecoin Opinion: The Non-Binding Text That Could End USDT Custody in the EU, and Europe’s Dollar Question
ESMA’s stablecoin opinion is not binding, but EU supervisors can use it to end USDT custody by January 2027. What it means for holders and Europe’s dollar ties.
The Bright Recap
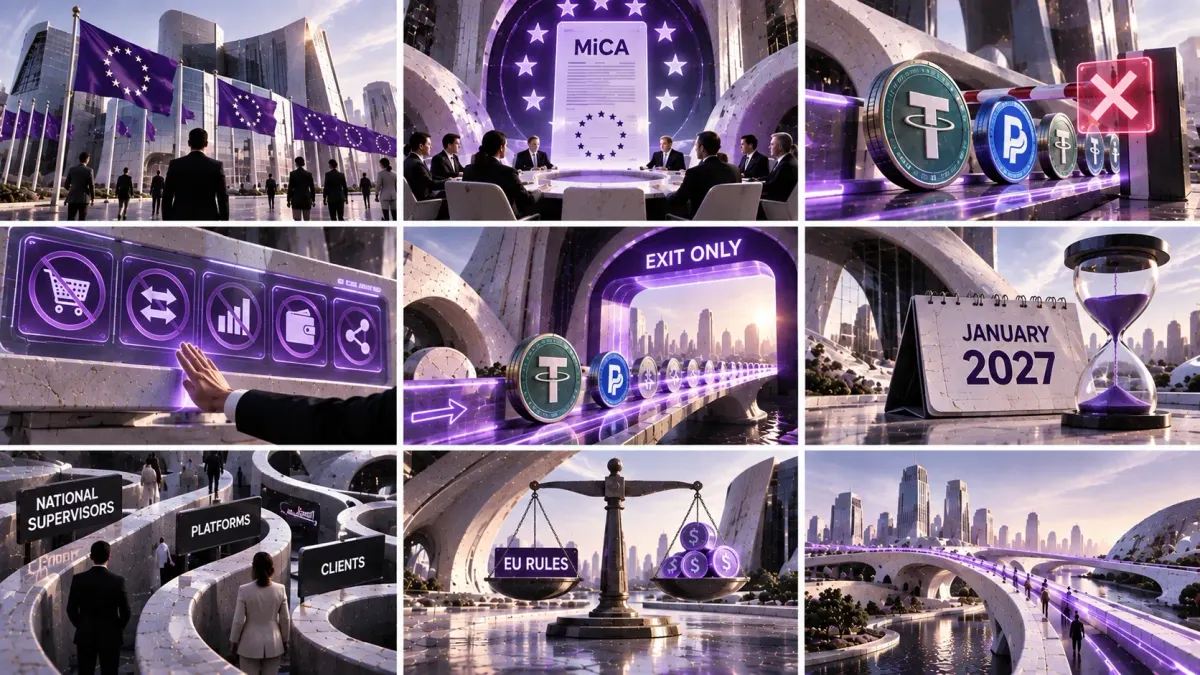
An ESMA opinion of 8 October 2026 asks EU national supervisors to stop licensed crypto platforms from offering any service, custody included, for stablecoins without MiCA authorisation. It is not binding until a supervisor applies it. USDT, about 60% of global stablecoin supply, is the main token affected, while the dollar-pegged USDC remains available.
To know more about this topic, read our related articles:
- How to check your exchange's MiCA licence
- How a MiCA licence protects and limits users
- The 37 banks behind a euro stablecoin
- Financial technology explained
- Cantica business reports
Bright Answers
Is the ESMA stablecoin opinion legally binding on crypto platforms?
No. It is addressed to national supervisors and applies to a platform only once the supervisor that licensed it adopts ESMA's reading. That supervisor can withdraw the licence of a platform that seriously breaches MiCA.
Can Europeans still hold USDT if supervisors apply the opinion?
Yes. The opinion covers services by licensed platforms, not ownership, so holders could keep USDT in a self-custody wallet, or sell it or convert it into a MiCA-authorised stablecoin during the exit period.
The European Securities and Markets Authority (ESMA) told national supervisors on 8 October that licensed crypto platforms in the European Union should stop every service linked to non-compliant stablecoins, the tokens whose issuers lack the authorisation required by the EU’s Markets in Crypto-Assets Regulation (MiCA). The ESMA stablecoin opinion covers trading, exchange and advice, and for the first time it also covers custody and transfers. ESMA asks supervisors to have remaining client holdings dealt with no later than three months after publication, which should fall around January 2027.
The opinion has no legal force of its own, and it names no token. Its practical weight falls on Tether’s USDT, the largest stablecoin without MiCA authorisation and a token pegged to the US dollar, along with PayPal USD, according to CoinDesk. A platform whose supervisor applies the opinion could only help clients sell, convert or move these tokens out, which places the opinion inside a wider European debate about how much of its digital money runs on dollars issued outside its rules.
Meet Cantica, the Fin-Tech intelligence system for custom reports to strategise your next business move.
What an ESMA opinion is and whether platforms must follow it
ESMA cannot make law. Its instruments sit on a ladder: MiCA itself binds everyone, technical standards drafted by ESMA become binding once the European Commission adopts them, and guidelines carry a comply-or-explain duty, under which ESMA can publish the reasons a national supervisor gives for not following them. Opinions sit lower, with no formal compliance procedure of their own.
This opinion rests on Article 29 of ESMA’s founding regulation, the provision that lets the authority build a common supervisory culture across member states. Its addressees are the national supervisors, such as BaFin in Germany, the AMF in France and Consob in Italy, rather than the platforms. A platform meets the opinion only when the supervisor that granted its licence applies it, and ESMA’s public register shows which supervisor that is, so anyone can check a platform’s licence in minutes.
That supervisor holds the decisive lever in practice. ESMA’s reading treats these services as a breach of the duty MiCA places on platforms to serve their clients’ best interests with honesty, fairness and professionalism, and MiCA requires supervisors to withdraw the licence of a platform that seriously infringes the regulation, including its rules protecting holders. ESMA has also said it will monitor how quickly national supervisors apply the opinion.
The reach is wide. The ESMA register listed 362 licensed crypto-asset service providers across 27 countries of the European Economic Area on 7 October, according to a count by Outrun Advisory, with 96 in Germany, 36 in France and 29 in the Netherlands. Each of them answers to a national supervisor that ESMA is now addressing.
A platform that disagrees has a narrow path. The EU Court of Justice held in a 2021 ruling involving the European Banking Authority that this kind of non-binding guidance cannot be annulled directly, although a national court can ask Luxembourg whether it is valid. A platform could therefore only contest its own supervisor’s decision at home and hope the question reaches the Court.
What the opinion asks supervisors to require
The ESMA opinion covers all nine services MiCA regulates: running a trading platform, exchanging tokens, executing orders, receiving and passing on orders, placing tokens, giving advice, transferring tokens, holding them in custody and managing portfolios. ESMA expects platforms to put technical, contractual and organisational controls in place so that EU clients cannot buy these tokens or add to their positions.
The reasoning starts from the issuer. MiCA attaches its main safeguards to the company that issues a stablecoin, and a platform cannot replace them, so ESMA presumes that offering any service around such a token breaches the platform’s duty to its clients.
ESMA adds three reasons:
- platforms would otherwise let issuers sidestep MiCA,
- authorised issuers would compete on unequal terms,
- and investors would lose confidence in a system that protects them in some places and not in others.
National supervisors may allow a short exit period for existing holdings only. A platform could then liquidate, convert, withdraw, transfer or safeguard the tokens, as long as the arrangement is time-limited, explained clearly to clients and closely supervised. ESMA excludes anything that helps a client buy, trade or promote the tokens.
From MiCA to the January deadline
The opinion is the latest step in a sequence that began when MiCA was published in June 2023.
| Date | Event |
|---|---|
| 9 June 2023 | MiCA published in the EU’s Official Journal |
| 30 June 2024 | MiCA’s stablecoin rules start to apply |
| 1 July 2024 | Circle’s USDC becomes MiCA-compliant through a French e-money licence |
| 13 December 2024 | Coinbase suspends USDT for European customers |
| 17 December 2024 | Tether invests in StablR, a Malta-licensed issuer of MiCA-compliant stablecoins |
| 17 January 2025 | ESMA statement: platforms stop trading non-compliant stablecoins, sell-only until 31 March 2025 |
| 31 March 2025 | Binance ends USDT spot trading for European users, who can still hold the token on the platform |
| 18 July 2025 | The US GENIUS Act, a federal framework for stablecoins, is signed into law |
| 20 October 2025 | European Systemic Risk Board recommendation on stablecoins issued jointly inside and outside the EU |
| 1 July 2026 | MiCA’s transition period for crypto platforms ends |
| 8 October 2026 | ESMA opinion extends the restrictions to every service, custody included |
| around 8 January 2027 | Deadline for supervisors to clear remaining holdings (our calculation) |
Source: The Bright Minded’s timeline, compiled from ESMA, the EU Official Journal, Circle, Coinbase, Tether, Binance, the US Treasury and the European Systemic Risk Board. The January 2027 date is our calculation from the opinion’s three-month deadline.
Custody is the change from January 2025
The January 2025 statement asked platforms to stop offering and trading these tokens and allowed sell-only services until the end of March 2025. Custody and transfers stayed available, according to an analysis of that statement by the law firm William Fry, because holding or moving a token does not amount to offering it to the public. Binance, for example, ended USDT spot trading for European users at the end of March 2025 while letting them keep the token on the platform, according to Cointelegraph.
The October opinion closes that gap by changing the legal basis. The 2025 statement relied on MiCA’s rules for offering stablecoins to the public, while the new opinion relies on the duty a platform owes its clients, which applies whether or not a service counts as an offer. No MiCA article explicitly bans a platform from holding an unauthorised stablecoin for a client, which is why custody survived the 2025 statement, and the new opinion reaches it through the client duty instead.
Why a signed warning does not change the answer
ESMA states that warnings, disclosures and client acknowledgements do not solve the problem, because clients cannot realistically assess the absence of protections at issuer level, and platforms would assess it differently from one another. A client who reads every risk notice and accepts it in writing would still be unable to opt back in.
The protection in question is concrete. A holder of an authorised e-money token, the MiCA category for stablecoins pegged to a single currency, has a legal claim against the issuer, which must redeem the token at par value at any time and without a fee. Issuers must also keep part of their reserves as deposits at EU banks, at least 30% and 60% for the largest tokens, according to the European Central Bank (ECB).
A platform can inform a client about the absence of those rights, but it cannot create them. The opinion follows that logic: fintech platforms cannot supply by contract a protection that only an issuer can provide.
What changes for people holding USDT
Ownership itself is untouched. The opinion covers services provided by licensed platforms and says nothing about people who hold tokens in their own wallets, so a European could keep USDT by moving it to self-custody before the exit period ends. The other routes the opinion leaves open are to sell the tokens or convert them into a stablecoin that MiCA authorises.
Self-custody asks more of the holder than an exchange account does. The holder alone keeps the recovery phrase that controls the wallet, nobody can restore access if it is lost, and the protections MiCA requires from platforms, such as the separation of client assets and a complaints procedure, have no provider to attach to. A holder without technical confidence who wants to keep USDT would have to take all of that on alone, which makes selling or converting the simpler choice for many.
Earlier MiCA decisions followed the same pattern, with licences that protect users while erasing their options. The opinion would turn custody on a licensed platform, the last regulated service still open to holders of these tokens, into an exit route.
How much of the stablecoin market the opinion touches
Dollar tokens dominate the market the opinion addresses. Stablecoins in circulation were worth about $306 billion on 9 October, according to DefiLlama, with USDT at about $184 billion and USDC at about $73 billion. Roughly 60% of the world’s stablecoin supply, by our calculation, sits in a token that licensed EU platforms would no longer hold for clients once supervisors apply the opinion.
Euro stablecoins remain small by comparison. The ECB’s Isabel Schnabel put their combined value at about €500 million in June, which by our calculation is about 0.2% of the global market. Circle also issues a euro token, EURC, under the same French licence that covers USDC.
The dollar behind the tokens Europe is restricting
The opinion’s reasoning is about investor protection, and it never mentions currencies. The tokens it affects most, however, are pegged to the US dollar, and the ECB has spent 2026 describing dollar stablecoins as a question of monetary sovereignty.
Ninety-nine per cent of the world’s stablecoins are denominated in dollars, Piero Cipollone of the ECB’s Executive Board said in Rome on 12 February, and he warned that stablecoins could draw deposits, payment fees and customer data away from European banks. Schnabel said in Seoul on 1 June that stablecoins could reinforce the dollar’s international dominance. The European Systemic Risk Board attributed part of the market’s growth since 2023 to US policies promoting dollar stablecoins, and in October 2025 recommended that the European Commission treat schemes in which EU and non-EU entities jointly issue the same token as not permitted under MiCA.
Washington describes the same tokens in the opposite terms. US Treasury Secretary Scott Bessent said on the day the GENIUS Act became law, 18 July 2025, that stablecoins would strengthen the dollar’s position as the world’s reserve currency and raise demand for the US Treasuries that back them. Tether reported about $120 billion of exposure to US Treasuries in the first quarter of 2025, at a time when USDT in circulation was worth about $149 billion, according to Cointelegraph.
MiCA carries a currency brake of its own. Articles 23 and 58 require a stablecoin pegged to a currency other than an EU member state’s to stop being issued once its use as a means of exchange passes 1 million transactions and €200 million a day, a limit that does not apply to e-money tokens in euros. European banks are building their own euro stablecoin through the Qivalis consortium, and the ECB is preparing the digital euro.
Where the line actually falls
The line ESMA draws runs between authorised and unauthorised issuers, and dollar tokens sit on both sides of it. USDC, pegged to the dollar, has complied with MiCA since July 2024 and remains fully available. Tether chose not to seek authorisation for USDT, and its chief executive Paolo Ardoino argued in May 2025 that MiCA’s requirement to hold reserves in European bank deposits would create risks for banks and for stablecoins.
Tether has still found a way into the European framework. It invested in December 2024 in StablR, which holds an e-money licence in Malta and issues euro and dollar stablecoins that comply with MiCA. The company that declined MiCA authorisation for its main product is therefore backing an issuer that holds it.
These facts describe a European system that keeps dollar stablecoins available while requiring their issuers to hold EU licences, keep part of their reserves in EU banks and stay under limits on everyday payments. The opinion adds one more requirement on the platform side, and its effect concentrates on the largest issuer that chose not to seek authorisation.
Europe’s rules accept dollar stablecoins as long as their issuers submit to European supervision, and Tether, the company behind the largest of them, has decided not to.
Editor’s note
Every piece published on The Bright Minded goes through careful verification, but mistakes can happen. If you spot an error, have additional information, or want to flag anything, write to rosalia@thebrightminded.com.