Agentic Bank Run: What AI Agents Would Move Out of Accounts Paying 0.1%
An agentic bank run means AI agents moving cash from checking accounts paying 0.1% to accounts paying 3.3% to 5%. Who loses, who gains, and how banks respond.
The Bright Recap
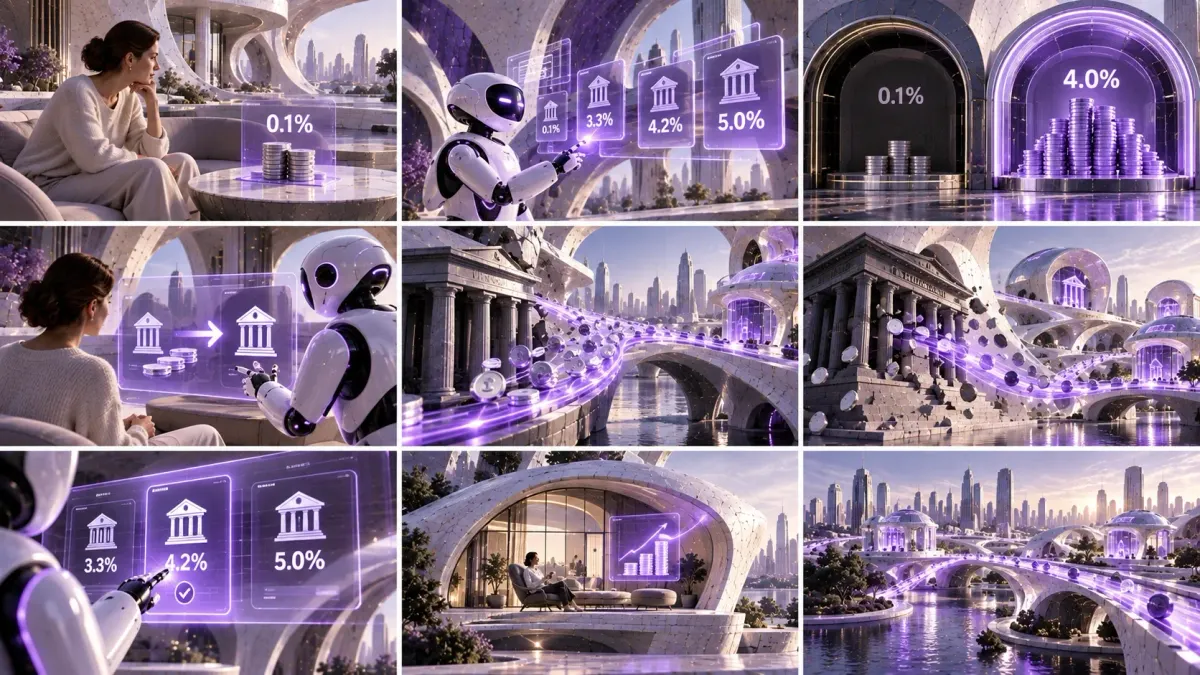
US checking accounts pay 0.1% on average, while higher-yield accounts pay 3.3% to 5%, and AI assistants could soon close that gap for households automatically. Apollo's chief economist calls the risk to banks an agentic bank run, and about $1.6 trillion of deposits earning no interest sit at JPMorgan Chase, Bank of America and Wells Fargo.
To know more about this topic, read our related articles:
- Why banks fought stablecoin yield
- ChatGPT's finance tool and the licence gap
- Financial technology explained
- Cantica business reports
Bright Answers
What is an agentic bank run?
It is a scenario, raised by Apollo chief economist Torsten Slok in September 2026, in which AI assistants automatically move household cash from low-paying bank accounts to higher-yielding ones, taking away banks' cheapest source of funding.
Can AI assistants move money between banks today?
The consumer tools launched so far have not been shown to. Meta's Muse reads account data through Plaid and ChatGPT's finance tool states it cannot move money, while JPMorgan plans its own automatic cash transfers during 2026.
An agentic bank run is the name for a simple idea: artificial intelligence (AI) assistants that move a household’s spare cash out of accounts paying almost nothing and over to accounts that pay between 3.3% and 5%. Torsten Slok, chief economist at Apollo, raised it in a note on 27 September, setting those rates against the 0.1% national average on US checking accounts, the American equivalent of a current account. The Financial Times has put the deposits that earn no interest at JPMorgan Chase, Bank of America and Wells Fargo at about $1.6 trillion, a figure PYMNTS cited on 8 October.
Most customers do not notice what their bank pays them, according to McKinsey. An agentic bank run would move money on which savers already forgo interest because they never compare rates, and an AI agent can do the comparing for them.
Meet Cantica, the Fin-Tech intelligence system for custom reports to strategise your next business move.
What an agentic bank run would actually move
Slok’s argument is that banks fund their loans partly with cheap deposits, and could see much of that cheap funding leave if every household let an agent chase the best rate. He described the result as a risk for the financial system as a whole. His note gives no estimate of how much money would move or how quickly.
The household side of the sum is easier to see. A balance of $10,000 left in a checking account at 0.1% earns $10 a year by our calculation, while the same amount at 4% earns $400. The reports citing the $1.6 trillion figure do not split it between households and businesses, so the household share is unknown.
Banks have defended cheap deposits in other arguments this year. Their opposition to stablecoins that pay yield during negotiations on the Digital Asset Market Clarity (CLARITY) Act rested on the same concern that the money would drain away.
Savers already leave most of the interest behind
McKinsey’s research on agentic AI in banking shows how wide the gap is in the US. Interest-bearing US checking accounts paid 0.07% on average in June 2025 and savings accounts 0.38%, while the best online savings accounts paid more than 4%. Balances in accounts paying no interest grew by 28% a year over the previous five years, against 3% for accounts that pay interest.
The tools to close that gap already exist for people who use them. Raisin, a fintech marketplace that lets savers, mainly in Europe and the UK, place money with partner banks offering higher rates, has gathered more than $80 billion across more than 250 banks, according to McKinsey. What an agent changes is who does the comparing and the moving.
AI assistants can see the money but cannot yet move it
The worry resurfaced after Meta launched its Muse assistant on 8 September, according to Reuters. Users can connect Muse through Plaid to their balances, transactions, investments and mortgage details, though Plaid’s announcement does not describe the assistant moving money between banks. OpenAI’s personal finance tool for ChatGPT, launched in May, also shows accounts while stating that it cannot move money or give formal advice, a gap we examined as advice without a licence.
People are already handing these assistants their money questions. A PYMNTS Intelligence survey of 2,439 US adults, carried out between December 2025 and January 2026, found that 37% of the most active AI users, about 10% of consumers, relied on AI platforms as their main finance and banking tool. The share among mainstream users doubled from 14% to 28% in a single month.
China tested the idea with a money fund in 2013
Yu’e Bao, a money market fund Ant Group launched in 2013, collected the spare cash sitting in Alipay wallets automatically, without the user doing anything. The fund reached about $268 billion by 2017, according to McKinsey’s analysis, and China’s central bank placed limits on it in 2018. McKinsey expects AI agents to go one step further, spreading cash across several banks and rebalancing it continuously.
McKinsey estimates that if 10% to 20% of consumers let agents move their cash automatically, net interest margins at European banks, the gap between what they earn on loans and pay on deposits, could narrow by 0.3 to 0.5 percentage points. It expects the effect to show up earliest where open banking, which lets customers share their bank data with other apps, is already established.
Banks are building the agent themselves
JPMorgan Chase is already planning to move its own customers’ cash. Jamie Dimon’s letter to shareholders, dated 6 April, says the bank plans for its Smart Cash feature to move money automatically from clients’ checking accounts into higher-yielding brokerage products during 2026, with AI later helping clients predict bills and cash needs.
Andrew Coombs, head of European financials equity research at Citi, considers worries about deposit flight overstated, according to a Reuters report on 1 October. He expects trust, reliability and regulation to hold back third-party agents, and banks to build AI tools into their own apps instead. He named the French, Dutch and German markets as the most at risk from AI-driven pricing pressure, with Spain and Ireland the best placed.
McKinsey’s suggestions for banks follow the same line: publish rates in a form software can read, offer savings pockets built for automatic transfers, and share part of the extra yield with customers so the balances stay put.
An agentic bank run would move money that has been earning its owners almost nothing, and the banks most likely to keep it are the ones that start paying them some of the difference.
Editor’s note
Every piece published on The Bright Minded goes through careful verification, but mistakes can happen. If you spot an error, have additional information, or want to flag anything, write to rosalia@thebrightminded.com.